

Robinhood Banking

- 2.33K Reviews
- 4.9
- Downloads
- 100,000+
Our take on Robinhood Banking from Appgk
Robinhood Banking is the kind of finance app I would consider when I want banking and investing-related money management to feel close at hand, rather than tied to a desktop routine. I tested it with a practical mindset: checking how it fits into quick mobile moments, what happens when a connection is unreliable, and whether its simple presentation is useful beyond the first few taps. The app is free, made by Robinhood, and carries an Everyone age rating, which makes it approachable for a broad audience.
Its store summary describes it as “Credit Card & Banking,” while the shorter description calls it “Robinhood Banking.” That wording sets a clear expectation: this is aimed at everyday financial access, not a spreadsheet-heavy accounting tool. In my experience, the appeal is strongest when I want to look at money information, make a timely decision, or keep a banking task within reach while away from a computer.
How Robinhood Banking feels when the network matters
The most important thing to understand is that a modern banking app is closely tied to connectivity. Robinhood Banking needs a dependable connection for the parts that involve current account information, financial activity, or actions that must reach Robinhood’s systems. On a strong home connection, the experience feels direct. On a busy mobile network, I become more aware that the app is not just a local dashboard sitting on my phone.
That matters during ordinary moments. Imagine I am standing in a shop and want to check whether a purchase fits my available balance before paying. The value of the app comes from seeing current information, not from looking at an old screen saved from an earlier session. If the connection is slow, the practical answer may arrive late, so I would not treat a loading screen as confirmation that a transaction has completed.
Best Parts of Robinhood Banking
Things to Keep in Mind About Robinhood Banking
I also found that connectivity changes how confidently I use financial actions. Browsing is one thing; submitting a banking request is another. If the signal drops just after I tap a confirmation control, I would pause rather than immediately repeat the action. Repeating too quickly can create uncertainty about whether the first attempt went through. My preferred workflow is to wait for the app to respond, then check the resulting account activity before trying again.
This is not a criticism unique to Robinhood Banking, but it is especially relevant here because financial apps carry higher consequences than a delayed social feed. The app’s clean mobile purpose is useful, yet it encourages quick decisions, and quick decisions are safest when the connection is stable enough to show a clear result.
News and Features Related to Robinhood Banking

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
What I do before relying on a transaction screen
I use a simple three-step habit. First, I check that the app has loaded the relevant information rather than assuming a partially visible screen is current. Second, I avoid tapping a sensitive action repeatedly if the interface pauses. Third, I return to the account activity or confirmation area after the network settles. This takes a little longer, but it reduces the chance of acting on an incomplete view.
That habit is one of the less obvious strengths of using a dedicated banking app: it puts the information in the same place where I am likely to make a decision. The trade-off is that convenience can make me impatient. Robinhood Banking is best used with a small pause when the connection is uncertain, especially for anything involving a balance, transfer, card activity, or other financial change.
Don't want to read the full review?
Using it in real mobile contexts
The app makes the most sense on a phone because financial questions often appear away from a desk. I might be comparing a planned purchase with the money available in an account, checking recent activity after using a card, or reviewing my position before moving on with the day. These are short sessions, and Robinhood Banking is more suitable for them than a desktop-first service that expects a long visit.
At the same time, mobile convenience should not be confused with complete financial planning. A phone is excellent for a quick check, but less comfortable for comparing many categories, reviewing long histories, or building a detailed household budget. If my main goal were full expense analysis, I would probably pair a banking app with a dedicated budgeting tool or use a larger screen. Robinhood Banking works better as an access point than as a replacement for every financial workflow.
Screenshots
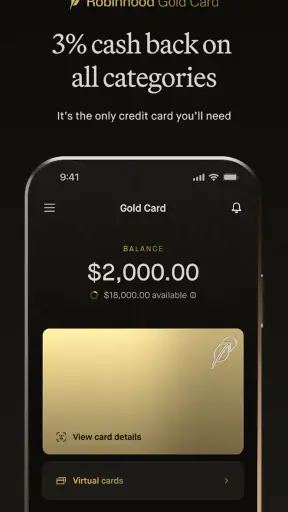
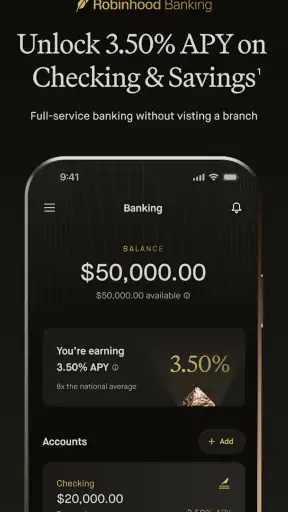
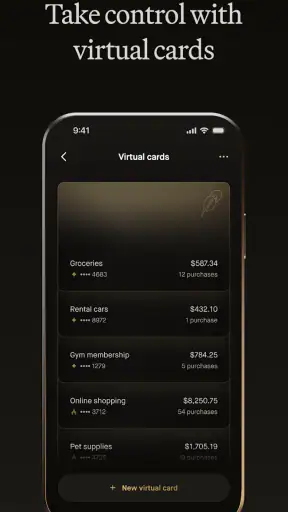
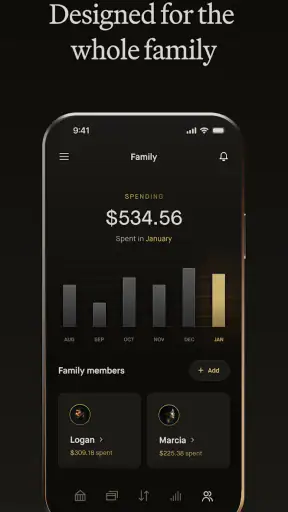
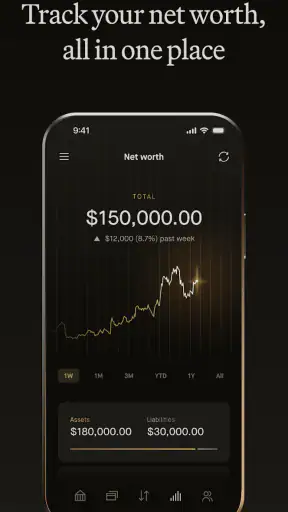
One realistic scenario is a commute. I notice a card purchase notification, open the app during a safe pause, and want to confirm whether the activity matches what I remember. If the train moves through areas with inconsistent reception, I would avoid making a second financial decision until the activity view is fully updated. The app is still useful in that situation, but the right benefit is awareness, not the promise that every action can be completed instantly.
Another scenario is travel. I may need to check money information in an unfamiliar place, where mobile data is congested or expensive. In that context, I would open the app only when I have a reliable connection, keep my questions focused, and avoid repeatedly refreshing. A short, deliberate session is more sensible than leaving the app open and expecting it to keep everything synchronized continuously.
For people who manage money across several services, the mobile setting also exposes a comparison issue. A traditional bank’s app may offer deeper account administration because it is built around a broader banking relationship. A separate investment platform may provide more specialized market tools. Robinhood Banking is appealing when I value a connected Robinhood experience and quick access, but it may not be the best single destination for someone who wants every possible banking feature under one roof.
Why the phone-first approach helps—and where it gets tiring
I like the reduced friction of opening one app instead of navigating a bank website in a mobile browser. The focused format makes a short check feel manageable. However, small-screen finance also increases the importance of reading carefully. A compact interface can make it tempting to skim labels, especially when I am distracted in a queue or on the move.
My practical advice is to use Robinhood Banking for intentional checks, not constant nervous refreshing. If I am waiting for an update, refreshing repeatedly does not make the underlying network faster and can make it harder to tell which screen is current. I would rather close the app, wait for a better connection, and reopen it when I can pay attention.
What happens when something fails
Connectivity problems are where my confidence in any finance app is tested. A stalled screen, an error message, or an interrupted session does not automatically mean that money has moved or that nothing happened. The safest response is to separate the technical problem from the financial result. I first look for a clear confirmation or updated activity, then decide whether another attempt is necessary.
This is also where Robinhood Banking’s usefulness depends on my own discipline. The app can present the tools, but I still need to keep track of what I attempted and when. If a screen freezes after I submit something, I make a note of the action rather than immediately pressing the same control several times. Once the connection returns, I check the account information before taking further action.
That recovery workflow is particularly important for users who are new to mobile banking. A familiar-looking button can encourage the assumption that the process is complete. I would treat the final status, confirmation, or resulting activity as the meaningful evidence—not the fact that a button accepted a tap.
There is a second kind of failure: information that looks outdated because synchronization is delayed. If I am checking a balance before a purchase, I allow time for the latest information to load. If the app cannot provide a clear current view, I postpone the decision or use another trusted channel. That may sound cautious, but it is exactly the behavior I want around personal finances.
Recovery habits that make the app less stressful
I recommend keeping a simple record of interrupted actions in my head or in a private note: what I tried, roughly when I tried it, and what result I expected. I do not record sensitive credentials. The purpose is only to avoid guessing after a connection problem. When the app becomes responsive again, I compare the visible activity with that expectation.
I also avoid judging the app solely by a single slow session. Mobile networks vary by location, congestion, and signal quality. A useful test is to try the same basic viewing task on a stable connection later. If the issue repeats under good conditions, that is a stronger sign of an app or account problem than one failed attempt in a poor-signal area.
Still, users who need guaranteed access during network outages should think carefully before making Robinhood Banking their only financial reference. A phone app cannot provide a dependable live banking experience when it cannot communicate with the relevant service. I would keep an alternative way to handle urgent needs, especially while traveling or managing time-sensitive payments.
Using it without wasting mobile data
Finance apps are not usually the biggest source of mobile data on a phone, but data-conscious habits still make sense. I do not leave Robinhood Banking open unnecessarily, and I avoid repeated reloads when a page is taking time. I open it for a specific purpose, let the information load, complete the review, and close it when finished.
This approach has another advantage: it keeps my attention on the financial task. Constantly checking an account can create noise without improving my decisions. A deliberate routine—reviewing activity after meaningful purchases and checking balances before planned spending—feels more useful than opening the app every few minutes.
When I am on a limited connection, I prefer to use a stable Wi-Fi network for longer reviews and reserve mobile data for short checks. I would not assume that a screen displayed during a weak connection is fully current simply because some content is visible. For financial information, completeness matters more than speed.
People sharing a phone or using a small data plan should also think about session habits. I sign out or secure the device according to my normal phone-security routine, avoid opening financial information in crowded places, and do not treat a public network as automatically trustworthy. These are not special Robinhood features; they are sensible boundaries around any banking app, and Robinhood Banking is no exception.
The practical trade-off between convenience and certainty
The app’s convenience comes from reducing the distance between a financial question and an answer. But the closer that answer is to an immediate decision, the more important it is to confirm that the information is current. I would rather spend an extra moment checking a refreshed view than make a purchase or repeat an action based on a screen that loaded incompletely.
This is also why I would not use it as a substitute for a written financial plan. Robinhood Banking can help me see what is happening, but seeing activity is not the same as understanding my monthly obligations. For careful budgeting, I still want a separate method that accounts for upcoming bills, irregular expenses, and longer-term goals.
Who will get the most from it
I think Robinhood Banking is a good fit for someone who already prefers Robinhood’s ecosystem and wants banking access in a mobile format. It is also worth considering for a person who values quick account checks and does not want to depend on a desktop browser for routine money tasks. The free price removes an obvious barrier to trying it, and the Everyone rating makes it broadly approachable from an age-label perspective.
The app has also attracted strong user response: it holds a 4.9 average from around 25 thousand ratings, with roughly 2.3 thousand written reviews. It has passed 100 thousand installs, which suggests that it is being used beyond a tiny test audience. I would treat those figures as signs of interest rather than proof that every user will find the same workflow comfortable.
It is less suitable for me when I need an all-purpose banking relationship with extensive administration, branch support, or a very detailed budgeting system. It may also be a poor match for someone who is uncomfortable making financial decisions from a phone or who frequently operates in places with unreliable connectivity. In those cases, a conventional bank app, desktop service, or broader personal-finance platform may be a better primary tool.
I would also skip it as my only option if I need specialized investment research or advanced portfolio analysis. The app’s banking identity is its clearest appeal. Choosing it should be based on how well that role matches my needs, not on the assumption that one mobile app must replace every other financial service.
Version, access, and day-to-day expectations
Robinhood Banking is currently listed as version 2.18.7 and requires Android 7.0 or later. That makes device compatibility worth checking before installation, particularly if I use an older phone. The app is free to install, but I would still read the relevant in-app terms carefully before using any financial service or making decisions about money.
The developer is Robinhood, so the app feels most coherent for people who recognize and want that broader brand environment. I would not choose it solely because it is free or because it has a high average rating. Those details can encourage a trial, but the real question is whether its mobile banking workflow matches the way I check, spend, and manage money.
Before relying on it for an important task, I would install it on my regular device, sign in through the normal process, and practice with low-stakes viewing. I would learn where current activity appears and how the app communicates a completed action. That small preparation is more valuable than waiting until I am traveling, rushed, or dealing with a weak signal.
My connectivity verdict
After using Robinhood Banking with connectivity in mind, I see it as a convenient mobile finance companion rather than an offline safety net or a complete replacement for every banking and budgeting tool. Its strongest moments are quick, intentional checks when I have a reliable connection and enough attention to confirm what I am seeing.
The main friction is not that mobile access is inherently difficult; it is that financial actions require more patience when a network is slow or an update is unclear. I can work around that by avoiding repeated taps, checking the resulting activity, and postponing important decisions when the app cannot show a dependable current state.
My recommendation is straightforward: choose Robinhood Banking if fast mobile access within Robinhood’s environment matters to you, but keep a careful recovery habit and a backup plan for urgent situations. For everyday awareness, it is approachable and easy to justify as a free app. For complex financial planning, specialized investing, or unreliable-connectivity situations, I would use it alongside a more suitable alternative rather than asking it to do everything.
Robinhood Banking FAQ
What is Robinhood Banking, and what services does it provide?
Robinhood Banking refers to the banking-related features available through the Robinhood financial app, including spending, cash management, direct deposit, transfers, and access to eligible savings or cash products depending on your location. It is designed to work alongside Robinhood’s investing services, but it is not a traditional full-service bank. Available features, terms, and account protections may vary by country and product.
Is money held in Robinhood Banking insured and protected?
Protection depends on the specific Robinhood product and how your money is held. Eligible cash may receive coverage through applicable government-backed insurance or other protections, but not every balance or investment is automatically covered in the same way. Before depositing money, review the account agreement, insurance limits, and disclosures in the app, especially if you plan to keep a large balance.
Can I use Robinhood Banking for direct deposit, bills, and everyday spending?
In supported regions, Robinhood may allow users to receive paychecks or government payments through direct deposit, transfer money, use a debit card, and manage everyday spending from the app. Availability can depend on eligibility, account verification, and local regulations. Users should confirm supported payment types, transfer limits, card fees, and processing times before replacing a traditional checking account.
Are there fees for using Robinhood Banking?
Robinhood commonly promotes low-cost or commission-free access to many services, but that does not mean every banking activity is free. Possible costs can include out-of-network ATM fees, expedited transfers, foreign transactions, returned payments, or charges associated with specific products. Fee schedules can change, so check the current disclosures in the app before making frequent withdrawals or international transactions.
What should I know about account access, verification, and customer support?
Opening and using a Robinhood Banking account generally requires identity verification and may involve providing personal, tax, and financial information. Transfers or withdrawals can occasionally be delayed by security reviews, compliance checks, weekends, or bank processing times. Customer support is primarily handled digitally through the app or website, so users who require branch access or immediate telephone assistance may prefer a conventional bank.











